Annual federal tax, both paths
Ordinary brackets, the standard or your itemized deduction, qualified dividends and long-term gains stacked with the IRS worksheet, the 3.8% net investment income tax, the $3,000 capital loss deduction with carryforward, and taxable Social Security per Publication 915.
Progressive state brackets
Every state with a broad income tax plus D.C., by filing status, with enacted future rate changes, state capital-gain treatment where modeled and Washington's capital gains tax. Enter custom brackets for any state, plus an optional local rate.
Moving states
Model a different state at payout. Choose whether your former work state can tax the payout, or apply the federal source-tax protection (4 U.S.C. §114) assumption at ten or more yearly installments.
Employer credit risk
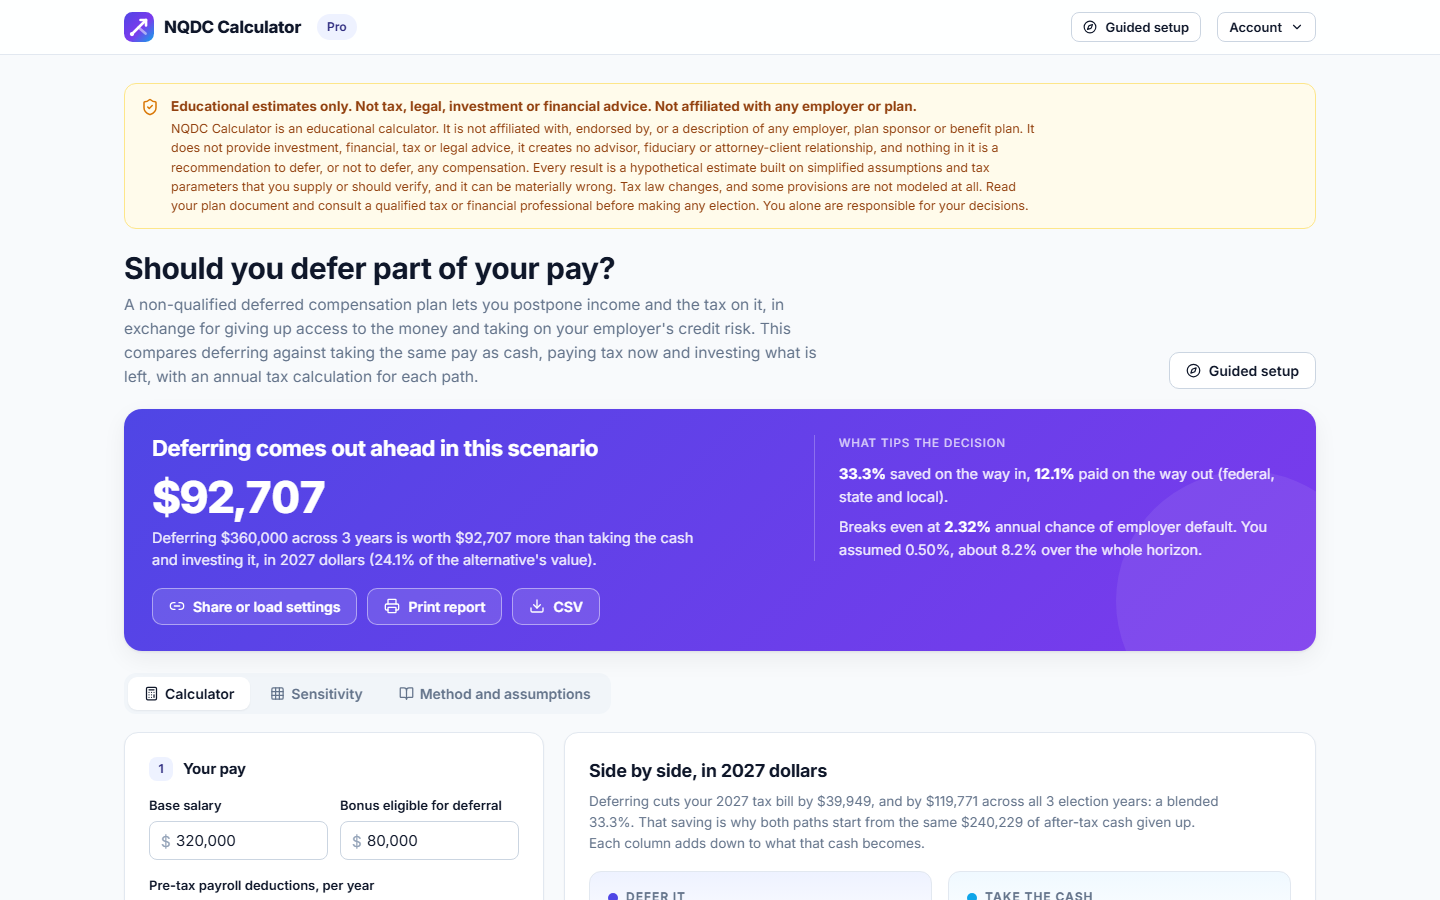
Deferred pay is an unsecured promise. Set an annual default probability and see the expected loss, plus the break-even risk at which deferring stops paying off.
Payout schedules
Lump sum or annual installments up to 15 years, with your other income, Social Security and pre-tax retirement withdrawals in each payout year.
Employer money
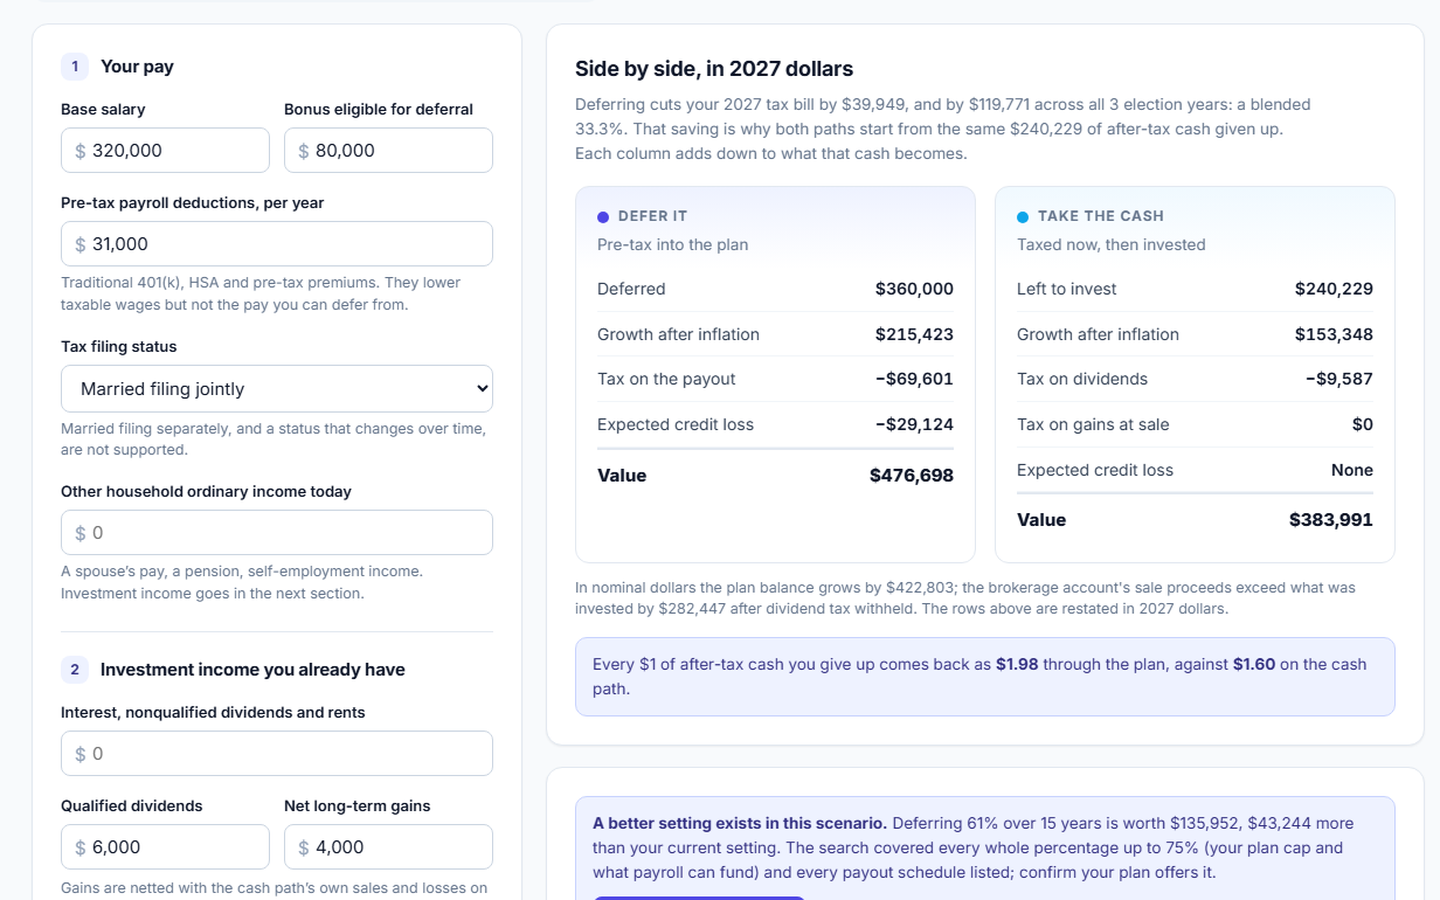
Employer credits on deferrals with vesting and the payroll tax they trigger, and any 401(k) employer contributions you would lose by deferring.
Optimizer and sensitivity
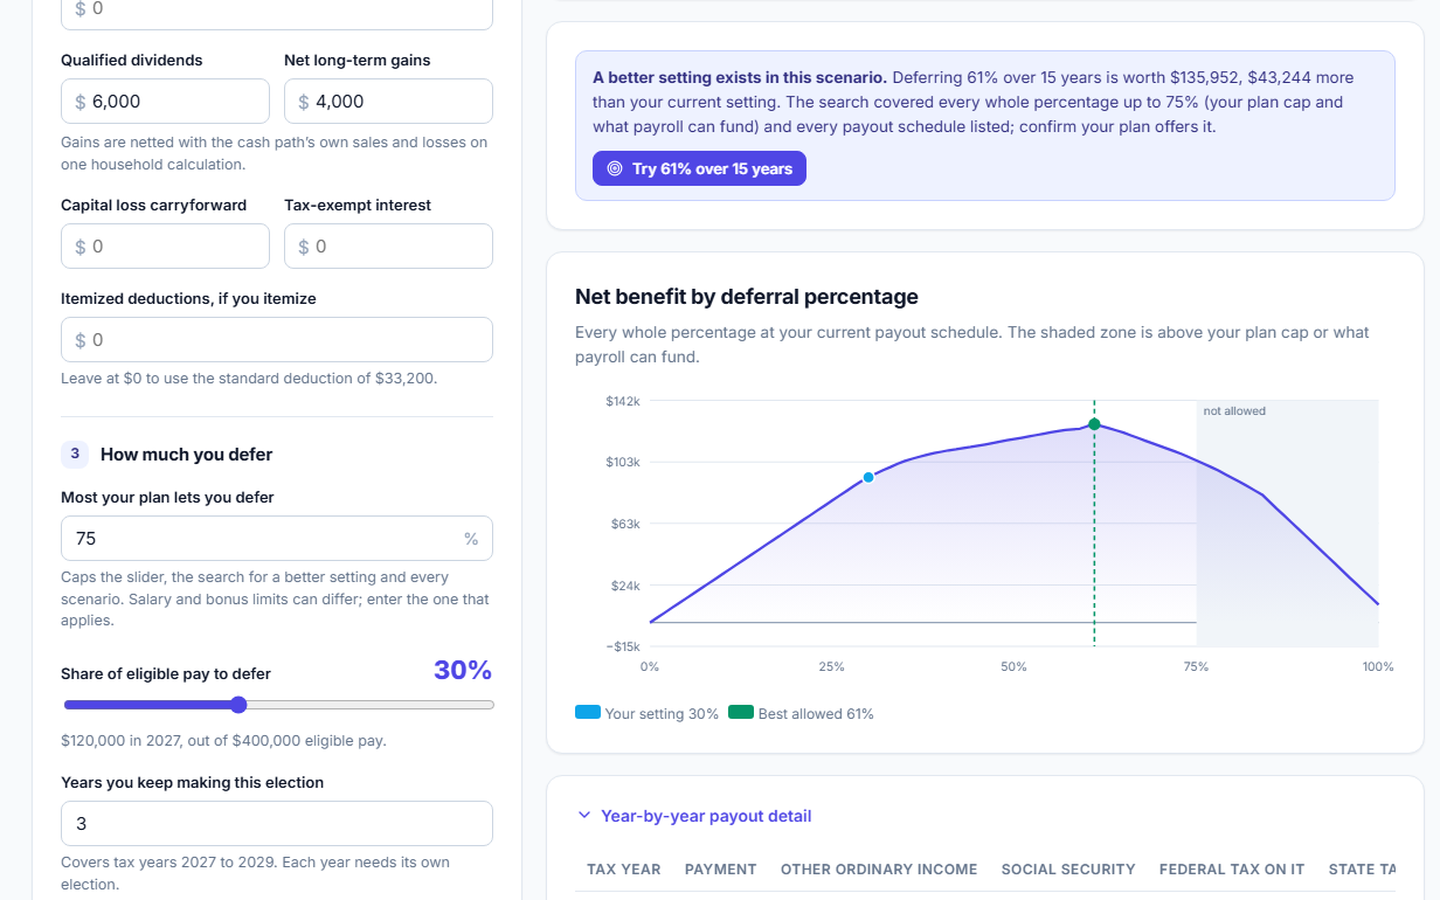
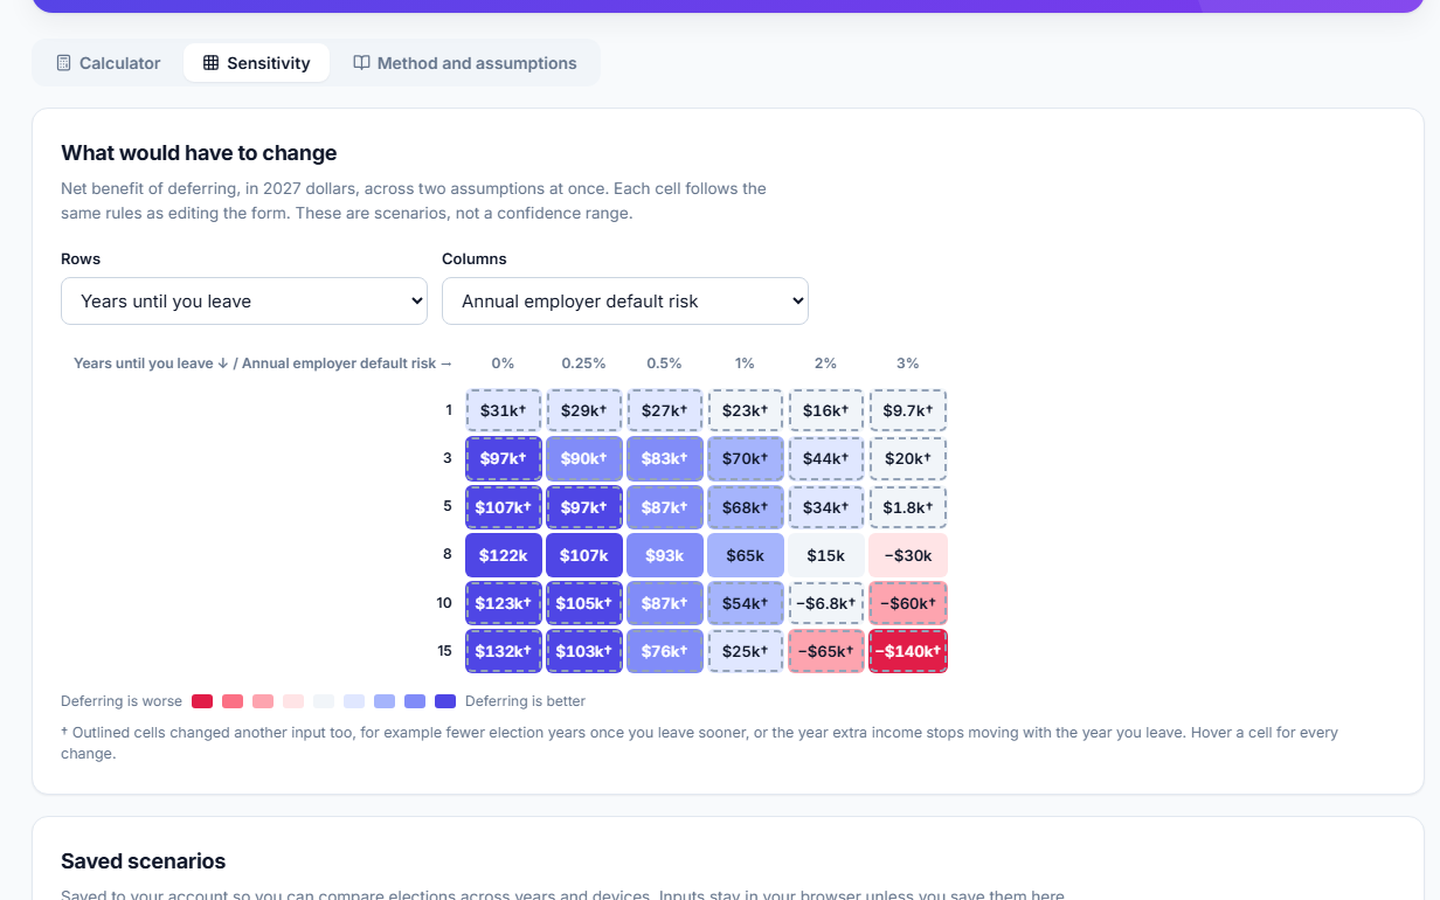
The best deferral percentage and payout schedule within your plan's limits, and a matrix of any two assumptions to see where the answer flips.
Exports and saved scenarios
A year-by-year ledger, a CSV with every input and tax parameter used, a printable report, and scenarios saved to your account.
Today's dollars
Results are restated for inflation, with an optional discount rate. Brokerage dividends are taxed every year and the account is sold on the same schedule as the payout.